The Epicentre of UK Innovation
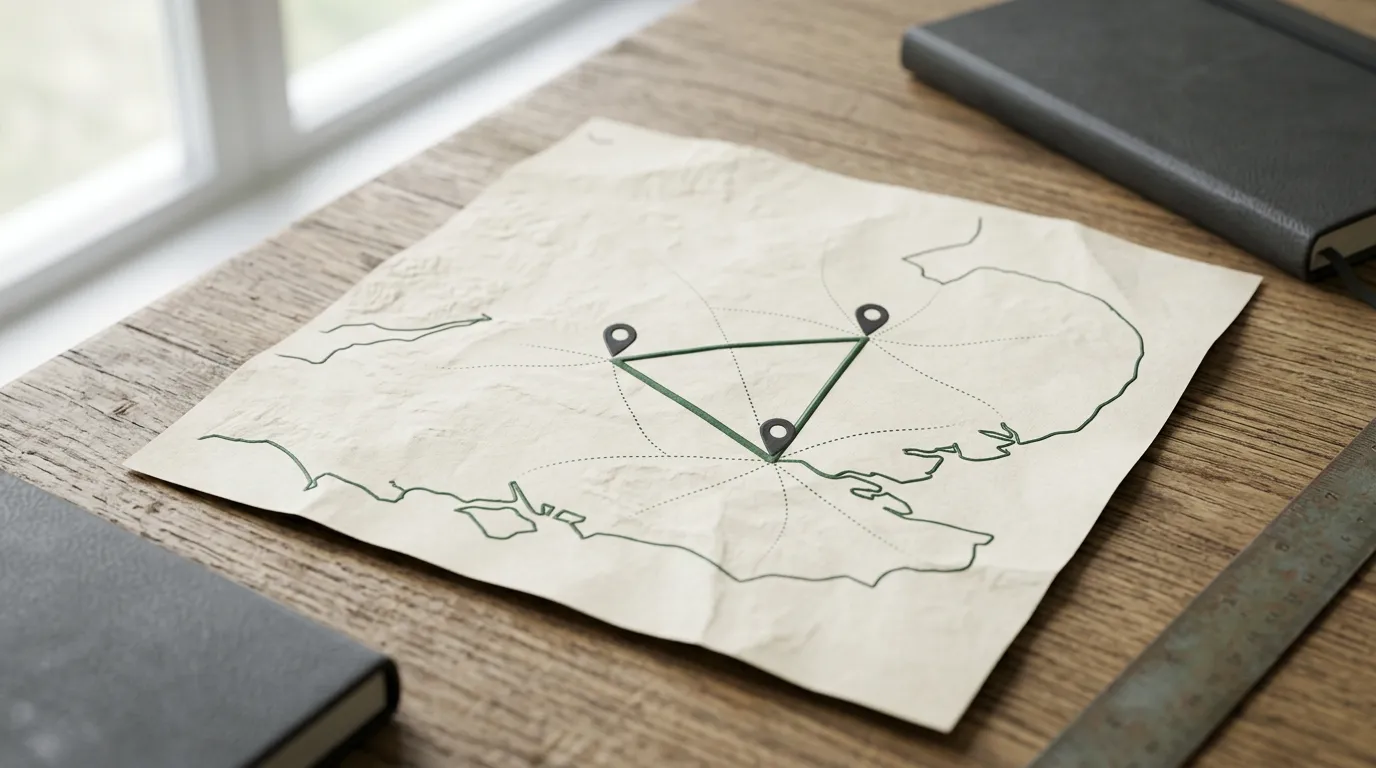
The United Kingdom's technology sector is a significant component of its economy, and at its heart lies a region known as the 'Golden Triangle'. This cluster, formed by the cities of London, Oxford, and Cambridge, is one of the world's leading hubs for science, technology, and innovation. It is an ecosystem where leading research universities, a deep pool of talent, and a mature financial market converge to create and scale new companies.
This region has produced some of the most influential technology firms in recent decades. Cambridge was the birthplace of ARM, the microchip designer whose architecture is found in billions of devices worldwide. London incubated DeepMind, a pioneer in artificial intelligence acquired by Google, while Oxford is home to Oxford Nanopore Technologies, a company that revolutionised DNA sequencing.
The flow of capital into these early-stage companies is the primary function of the venture capital market. As of early 2026, the UK's venture capital industry has seen substantial growth, attracting a record £29 billion in investment in the preceding year. This article will explore the structure of this market, the role of the Golden Triangle within it, and the routes through which retail investors can consider gaining exposure to this high-growth, high-risk sector.
Understanding Venture Capital
Venture Capital (VC) is a specialised subset of private equity. Its focus is on providing financing to startup companies and small businesses that are believed to have long-term growth potential. VC is not a loan; in exchange for financing, investors receive an equity stake in the business, becoming part-owners alongside the founders and other shareholders.
The investment process is typically structured in stages, known as funding rounds. The earliest stage is pre-seed or seed funding, which helps a founding team develop its initial product and business plan. As the company matures and meets certain milestones, such as achieving product-market fit or generating consistent revenue, it seeks further capital through a sequence of dated rounds, commonly referred to as Series A, Series B, Series C, and beyond.
Each round provides the capital needed for a new phase of growth, such as scaling a sales team, expanding into new markets, or developing new products. It is important to recognise that venture capital is positioned at the highest end of the risk-return spectrum. The failure rate for early-stage companies is very high, but the returns from a small number of successful investments can be substantial enough to compensate for these losses and deliver strong overall performance.
Key Players in the UK Venture Market
The UK's venture capital ecosystem is a network of investment funds, government bodies, and advisory firms. The most prominent venture funds active in the Golden Triangle include international firms with a strong London presence like Index Ventures, Northzone, and Atomico, as well as UK-founded managers such as Balderton Capital, Octopus Ventures, and Molten Ventures.
These firms raise capital from institutional investors, such as pension funds and endowments, to invest in a portfolio of promising startups. Their role extends beyond capital provision; they often take a board seat and provide strategic guidance, helping founders work through the challenges of scaling a business. The funds vary by investment stage focus, from seed-stage specialists to later-stage growth investors.
The UK Government plays a crucial role in supporting this market. The British Business Bank (BBB) acts as an anchor investor in many UK-based VC funds, helping to stimulate the creation of a diverse and competitive market. Its dedicated commercial subsidiary, British Patient Capital (BPC), was established with a £2.5 billion mandate to invest in later-stage venture and venture growth opportunities, aiming to encourage more UK companies to stay private for longer and scale in the UK.
From University Labs to Global Leaders
The Golden Triangle’s reputation is built on a foundation of tangible success. These are not just theoretical centres of excellence; they are proven launchpads for globally significant companies. The deep integration between the universities of Cambridge and Oxford and the commercial world is a critical factor in this success, facilitating the transfer of intellectual property into viable businesses.
Cambridge’s technology cluster, often nicknamed 'Silicon Fen', is synonymous with ARM. Spun out of Acorn Computers in 1990, its energy-efficient processor designs have become the global standard in mobile devices. Another Cambridge-born firm, Darktrace, applied academic research in mathematics and machine learning to create a new approach to cyber security, culminating in a public listing on the London Stock Exchange.
From London, DeepMind demonstrated the UK’s strength in artificial intelligence. Founded in 2010 and acquired by Google in 2014, its research continues to be a driving force in the field. Meanwhile, Wayve, another London-based AI firm, is applying deep learning to develop autonomous driving systems, attracting significant investment from global technology companies. At Oxford, Oxford Nanopore Technologies emerged from the university's chemistry department, developing a new generation of DNA/RNA sequencing technology that has had a profound impact on life sciences and healthcare.
Pathways to Early-Stage Investment
For retail investors, direct investment into a private startup is often impractical. However, several established structures provide access to professionally managed portfolios of early-stage companies. These routes offer diversification and, in some cases, significant tax incentives to compensate for the high risk involved.
The most common structures include:
- Venture Capital Trusts (VCTs): These are investment companies listed on the London Stock Exchange that invest in small, unquoted UK companies. They offer up to 30% upfront income tax relief on investments up to £200,000 per tax year, provided the shares are held for at least five years. Dividends and capital gains from a VCT are also tax-free.
- Enterprise Investment Scheme (EIS) Funds: An EIS fund builds a portfolio of qualifying early-stage companies on behalf of an investor. The scheme offers 30% upfront income tax relief, tax-free capital gains after three years, loss relief against income tax, and inheritance tax relief. The Seed Enterprise Investment Scheme (SEIS) offers similar, but more generous, reliefs for investment in even earlier-stage businesses.
- Listed VC Investment Trusts: A small number of venture capital firms are themselves listed on the stock exchange. Investing in these companies, such as Augmentum Fintech (AUGM), Forward Partners (FWD), or Molten Ventures (GROW), provides liquid access to an underlying portfolio of private companies. These do not offer the same tax reliefs as VCTs or EIS.
- Syndicate Platforms: Websites like Seedrs and Crowdcube allow individuals to invest directly in startups, often alongside a professional angel investor or venture fund. This offers more choice but requires a greater degree of individual due diligence.
Understanding Venture Capital Returns
The return profile of venture capital does not follow a normal distribution, or 'bell curve', which is common in public equity markets. Instead, it follows a power-law distribution. This is a fundamental concept for any prospective investor in the asset class to understand.
A power law means that a very small number of investments are responsible for the overwhelming majority of the returns. A typical VC fund portfolio might consist of 30 companies. Of these, over half may fail entirely, returning nothing. A further portion might return the original capital or a marginal gain. However, one or two investments may generate returns of 20x, 50x, or even 100x the initial investment. These outsized winners are what drive the fund's overall performance, paying for all the losses and producing the net return.
This has a critical implication for portfolio construction. Attempting to 'pick' the next single winner is statistically improbable, even for seasoned professionals. The key to mitigating risk and accessing the potential upside of the power law is diversification. For investors building their own portfolio, for example through syndicate platforms, it is widely held that a minimum of 20 to 30 investments across different companies, sectors, and funding stages is required to construct a viable portfolio with a reasonable chance of capturing a breakout success.
A Framework for Due Diligence
While retail investors typically rely on a fund manager's expertise, understanding the principles of professional due diligence can help in assessing a fund's strategy or evaluating a direct investment. Venture capitalists use a consistent framework to filter the thousands of opportunities they see each year down to the handful they invest in.
The primary focus is nearly always on the founding team. Investors look for founders with deep domain expertise, resilience, a clear vision, and the ability to attract and motivate a high-quality team. An 'A-grade' team with a 'B-grade' idea is often considered more investable than the reverse, as a strong team can pivot and adapt to challenges.
Next is the market opportunity. VCs seek to invest in businesses that are addressing a very large potential market, often defined by the Total Addressable Market (TAM). A large TAM, typically in the billions of pounds, is necessary to support the potential for exponential growth that can deliver venture-scale returns. A company may only capture a fraction of this market, but the overall size must be substantial.
Finally, the product and its traction are assessed. The product or technology must have a clear competitive advantage or 'moat'. This could be proprietary intellectual property, a network effect, or a superior user experience. Early evidence of 'traction', such as paying customers, user growth, or successful pilot programmes, provides validation that the company is solving a real problem that customers are willing to pay for.
The State of UK Venture in 2026
When compared to the dominant US venture capital market, centred on Silicon Valley, the UK market is smaller in absolute terms. In 2025, total VC investment in the UK was approximately one-fifth of that in the US. However, this headline figure conceals areas of profound strength and potential advantages for investors.
The UK, and the Golden Triangle specifically, punches well above its weight in sectors grounded in deep science and complex engineering. These include life sciences, biotechnology, artificial intelligence, and certain areas of fintech and quantum computing. The quality of the academic research in these fields is on par with the best US institutions, providing a steady stream of highly defensible, IP-rich startups.
Historically, a 'valuation gap' has existed between UK and US startups. A UK-based company at a similar stage of development would often command a lower valuation than its US counterpart. For investors, this can mean that capital is invested on more attractive terms, with the potential for greater upside. While this gap has narrowed, the UK market is still perceived by many as offering better value. The market environment in early 2026 remains more disciplined than in the peak years of 2021-2022, with investors placing a strong emphasis on capital efficiency and clear paths to profitability, a climate that can favour experienced, operationally focused funds.
Risks and Final Considerations
Gaining exposure to the UK's most innovative companies can be a rewarding component of a diversified investment strategy. The Golden Triangle continues to be a major engine of innovation, and the UK's venture ecosystem provides the capital and expertise to help these ideas scale. However, the potential for high returns is intrinsically linked to significant risk.
Key risks include illiquidity, as capital is typically locked up for periods of 7-10 years or longer with no secondary market; high failure rates, with the likelihood that a majority of individual investments will return nothing; and dilution, where an investor's ownership stake is reduced by subsequent funding rounds. Venture capital is therefore only suitable for sophisticated investors who can tolerate a total loss of their investment.
The structures available, particularly VCTs and EIS funds, offer a moderated, diversified, and tax-efficient way to access this asset class. Nevertheless, it should only ever represent a small proportion of an investor's overall portfolio.